Does My Auto Insurance Cover a Rental Truck? The Answer May Surprise You
Many people assume that if their personal auto insurance covers them while driving their own vehicle, it will also cover any vehicle they rent.
That may be true for many passenger cars and SUVs, but rental trucks are a different story.
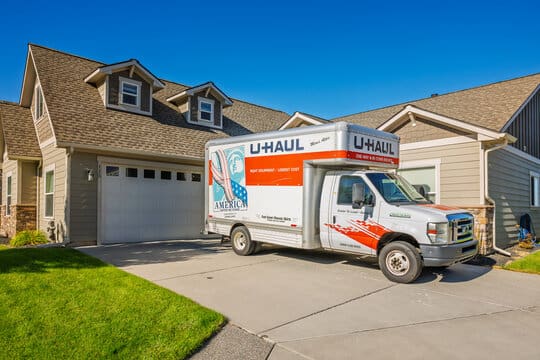
Whether you’re renting a U Haul, a cargo van, or a box truck for a day, your personal auto policy may not automatically provide coverage. Understanding the difference before you get behind the wheel can help you avoid an expensive surprise.
Why Rental Trucks Are Different
Personal auto insurance policies are written to insure private passenger vehicles. These typically include vehicles such as:
-
Cars
-
SUVs
-
Pickup trucks
-
Minivans
Rental trucks, box trucks, and many cargo vans are often classified differently because they are designed primarily to transport cargo rather than passengers. Depending on the size and type of vehicle, they may be considered commercial or business-type vehicles under your insurance policy.
Because of that, many personal auto policies either limit coverage or exclude these vehicles altogether.
Don’t Assume Rental Car Coverage Applies
One of the biggest misconceptions is:
“My policy covers rental cars, so it must cover rental trucks too.”
Not necessarily.
The rental vehicle coverage found in many personal auto policies often applies only to private passenger vehicles. A box truck or moving truck may fall outside that definition, even if you’re using it for personal reasons.
The only way to know for certain is to review your specific policy language or speak with your insurance advisor.
What Could Be Left Uncovered?
If your personal auto policy doesn’t extend coverage, you could be responsible for costs such as:
-
Damage to the rental truck
-
Damage you cause to another person’s property
-
Injuries to others if you’re at fault in an accident
-
Damage to items being transported
-
Loss of use charges or other fees assessed by the rental company
Coverage varies by carrier and policy, so these examples may not apply in every situation.
What About My Credit Card?
Some credit cards advertise rental vehicle protection, but those benefits frequently exclude:
-
Box trucks
-
Moving trucks
-
Cargo vans
-
Commercial vehicles
Before relying on your credit card benefits, review the terms carefully to see what types of vehicles qualify.
Should You Purchase the Rental Company’s Coverage?
Most truck rental companies offer optional protection plans that may include:
-
Physical damage protection
-
Supplemental liability coverage
-
Cargo protection
-
Medical or accident benefits
Whether those coverages make sense depends on your existing insurance and your comfort with the financial risk. Before declining them, it’s worth understanding exactly what your own policy does and does not cover.
Questions to Ask Before You Rent
Before driving away in a rental truck, ask your insurance agent:
-
Does my personal auto policy cover this specific type of rental truck?
-
Are there vehicle weight or size limitations?
-
Does my liability coverage extend to this vehicle?
-
Is damage to the rental truck covered?
-
Are there any exclusions I should know about?
A quick phone call can provide clarity before you’re responsible for a vehicle that may cost tens of thousands of dollars to repair or replace.
The Bottom Line
Not every rental vehicle is treated the same under a personal auto insurance policy.
While many policies extend coverage to passenger rental cars, rental trucks, box trucks, and similar vehicles may be excluded because they are not considered private passenger vehicles. Assuming you’re covered without verifying your policy could leave you responsible for significant out-of-pocket costs.
If you’re planning to rent a truck for any reason, take a few minutes to review your insurance coverage before picking up the keys. It’s one of the simplest ways to avoid an expensive surprise.